
Today we feature an infographic about how the current Latin population trends could affect the future real estate market.

Today we feature an infographic about how the current Latin population trends could affect the future real estate market.
A real estate appraisal is the process of determining the value of a newly build property, the resale value of a residential property, or evaluating properties for investment purposes. The appraisal is a report of many crucial details about the subject property and creates comparisons to similar ones in the neighborhood.
When an individual applies for a mortgage, the lender will require the property to be appraised by one of their certified appraisers. The cost, normally around $300 or higher depending on the property, is usually paid by the buyer outside of closing.
The appraiser will start the appraisal with a thorough physical inspection of the property inside and out. Also, they will look at courthouse records, recent real estate reports, and other numerous sources for more information on the subject property.
There are two different methods for conducting appraisals for residences:
The sales comparison approach is based upon comparing the subject property with a few similar homes that have been recently sold in the neighborhood. These are often referred to as the comparables. Analysis will focus on comparing specific bits of information, such as the square footage, style, age, lot size, and various other features of the homes.
The cost approach is mostly used for homes that have just been built and based upon the reproduction costs. This analysis will involve the appraiser estimating the cost to cover replacement of the property if it were to be destroyed. Land value and depreciation can also be added in to determine the value.
The real estate appraisal report will contain:
Overall, a real estate appraisal is more than just another cost or hassle added to the buying process. It is protection that will help everyone make informed decisions, so that a fair and reasonable price for market value can be formed.
It seems that Americans are continuing to dream of homeownership, at least according to JPMorgan Chase’s recent survey.
A total of 87% of those surveyed said owning a home is something they dream about.
“Owning a home is at the heart of most Americans’ dreams,” said Kevin Watters, CEO of mortgage banking at JPMorgan Chase. “And people are saving as much as possible to achieve homeownership.”
Of those surveyed, 66% believe housing is a good financial investment and 75% see it as a crucial part of raising a family.
“Owning a home will not only give my husband and me pride and roots, but it will also bring pride in my children and respect from my friends and family,” said one respondent.
Compared to six months ago, nearly two times as many potential first-time homebuyers are optimistic about being able to put money down on a home over the next six months.
Overall, 56% of consumers believe their finances will improve over the next six months, while only 8% believe they will worsen.
“First-time home buyers are crucial to the housing market and the overall economy – and to their communities,” Watters said. “As families buy their first home, they are investing in their communities and enable other families to move up. That will eventually spur more new construction, generating additional jobs.”
Original post at http://www.housingwire.com/fastnews/2013/03/15/survey-shows-homeownership-still-american-dream.

The housing slowdown may have been accompanied by an inability for potential homeowners to obtain mortgages, but the latest Fannie Mae National Housing Survey shows movement on the mortgage consumption-front.
For the month of November, 51% of survey respondents said it would now be easier to obtain a mortgage. This larger vote of confidence suggests tighter lending standards may be easing enough to grant more credit access.
Overall confidence in housing is up somewhat, with 14% of those interviewed believing home prices will go up in the next 12 months, a four-percentage point hike from the previous month. Twenty-three percent of survey respondents believe it’s a good time to sell a home, up 5-percentage points from October.
This is the highest rating of confidence since the survey’s inception more than a year earlier, the GSE said. In addition, 67% of the survey respondents said they would buy if they had to move in the near future.
The Fannie Mae November survey, which is the result of 1,001 interviews with Americans, concluded that consumer attitudes towards the economy and housing market are improving.
Doug Duncan, senior vice president and chief economist of Fannie Mae, noted that 11 of the national housing survey indicators evaluated by Fannie Mae are “at or near their two-and-a-half-year highs.”
About 44% of Americans believe the economy is now on the right track, and only 50% say it’s on the wrong track, which is 25-percentage point decline over the past year. The small gap between those two indicators suggests more improvement in overall economic confidence.
The number of survey respondents who foresee an increase in mortgage rates jumped 4 percentage points to 41%.
Respondents expecting home prices to fall over the next year rose by 4 percentage points to 14% over the previous month, while the number who expect home prices to go up over the next 12 months edged up to 37%.
Americans also seem more confident in their own financial situations, but remain worried the fiscal cliff will put them in worse shape next year. 18%, up 5 percentage points, felt that their personal financial situation would get worse over the next 12 months.
56% of respondents expect their household expenses to remain the same when compared to a year earlier.
Originally posted at HousingWire.com.
Mortgage bankers and Realtors are warning that it could become even harder for borrowers to qualify for a home loan early next year as the industry faces a barrage of new rules.
Regulators are preparing to release the language of two rules taking effect in January to set standards for non-abusive lending and require banks to hold a slice of risky mortgages on their books. In addition, U.S. banking overseers must also complete new capital standards mandated in the international Basel III accords next year.
The housing rules, coming almost simultaneously, may overlap or conflict, creating what National Association of Realtors President Maurice “Moe” Veissi called a “perfect storm” of regulation.
“There’s this intersection of policies that are absolutely not being considered by this massive array of institutions, all involved in deciding the future of homeownership and rental opportunity,” David Stevens, president of the Mortgage Bankers Association, said in an Oct. 22 speech at the association’s annual conference in Chicago.
Mortgage credit is already tight. U.S. regulators including Federal Reserve Chairman Ben S. Bernanke and Shaun Donovan, secretary of the U.S. Department of Housing and Urban Development, have expressed concern that banks are preventing qualified borrowers from taking advantage of interest rates driven to record lows by the Fed’s quantitative easing strategy.
James Parrott, a member of President Barack Obama’s National Economic Council who advises on housing issues, told mortgage bankers that the administration is still concerned.
“How do you correct for what happened in 2005, but not do so in such a way that we’re stuck where we are today, where there’s not nearly enough liquidity?” Parrott said at the MBA conference. “We clearly haven’t threaded the needle yet.”
Borrowers whose loans closed in September had an average credit score of 750, which would place them in the top 40 percent of Americans, according to Ellie Mae (ELLI), a Pleasanton, California, company that provides automation solutions for the mortgage industry. Those buyers made down payments averaging 22 percent. The interest rate on a 30-year fixed-rate mortgage averaged 3.37 percent in the week ended Oct. 18, according to Freddie Mac.
The housing market has been gaining steam in recent months, with online real-estate listing firm Zillow Inc. (Z) reporting yesterday that home prices jumped 1.3 percent in the third quarter, the largest gain since 2006. At the same time, about 28 percent of existing-home sales are all-cash transactions as investors snap up distressed inventory.
Consumer advocates, who question whether high credit standards are really just a response to regulation, say the industry’s fears are overblown.
“All of these rules are reactions to the failure to regulate at all over the last decade,” said Alys Cohen, a staff attorney at the National Consumer Law Center. “The rules don’t need to be in lockstep in order to provide reasonable oversight.”
The next few months will usher in a new implementation phase of the government response to the financial crisis of 2008 as regulators begin to unveil exactly how they will set limits intended to prevent another housing bubble.
The Consumer Financial Protection Bureau is briefing other regulators about its plans for the qualified mortgage rule, which will require lenders to determine borrowers’ ability to repay loans. If banks meet the standards for a non-abusive mortgage set in the rule, they’ll be offered a degree of legal protection.
Lenders say they’ll probably make only the safest mortgages as defined by the rule, commonly known as the QM regulation, after it is issued.
“QM will, in my mind, largely define the market,” Michael J. Heid, president of Wells Fargo (WFC) Home Mortgage, said at the MBA conference on Oct. 22.
The CFPB, which faces a Jan. 21 deadline, told regulators last week it is considering issuing a rule that would offer the strongest legal protections for loans to borrowers spending less than 43 percent of their income to repay debt. That would include about 80 percent of government-backed loans, according to data from the Federal Housing Finance Agency.
Once the QM rule is set, regulators including the Fed, Federal Deposit Insurance Corp. and Securities and Exchange Commission will write a second measure with a similar name: the qualified residential mortgage rule. The QRM rule will require lenders to retain stakes in risky mortgages when they package them into securities.
At the same time, regulators have proposed a set of standards under the Basel III agreement that would require banks to hold more capital against risky mortgages. A deadline for public feedback on the proposal was Oct. 22. The agencies are going to complete the language and phase in the rule beginning next year.
The MBA last week wrote a letter urging regulators to abandon their Basel III proposal on the grounds that it would hurt lending.
Veissi of the Association of Realtors also sent a letter raising concerns. “The sheer volume of regulations surrounding the mortgage-finance business has resulted in consolidating and constraining the number of institutions offering mortgage credit to consumers,” he wrote.
Consumer advocates say they agree that the rules are complex and must be carefully calibrated. However, they say, the mortgage industry needs to be more judicious with its complaints.
“Unfortunately, the mortgage lobby is the boy who cried wolf,” Julia Gordon, director of housing finance and policy at the Center for American Progress, said in an e-mail. “They fight any and every regulation and routinely insist that the [fill in the blank] rule will increase the cost of credit or reduce access to credit, which makes it difficult for the regulators to figure out when that’s actually true.”
Federal Financial Analytics, a Washington-based consulting firm, released a study yesterday analyzing possible unintended consequences of overlapping mortgage rules.
Karen Shaw Petrou, author of the study commissioned by the Securities Industry and Financial Markets Association, said the rules will shut out less-than-perfect borrowers.
“Regulators in every cubicle at all of the agencies are tightening each of their rules so drastically that the combination of all of them will stifle a return of private capital to securitization, blocking constructive change at the GSEs to end their conservatorship and limiting credit availability for all but the most gold-plated borrower,” Petrou said in an e-mail.
Parrott, the Obama administration official, said the rules could always be changed if they don’t work.
“Given where the market is today, I’m actually optimistic that we can land these regulations in a pretty good place,” Parrott said. “I think the objective everybody shares is a more stable, healthy system going forward that maintains broad access to credit.”
Original Post on Bloomberg BusinessWeek here: Mortgage Lenders See Tighter Credit Under New U.S. Rules
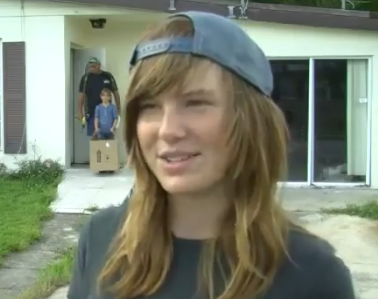
Willow Tufano is a 15 year old girl that has just purchased her second investment home in Port Charlotte, FL.
She found this steal on the MLS for $17,500 and began renovations on Monday.
Where does Tufano get the money to buy houses? She finds free items, fixes them up, and sells them on Craigslist. She saved up half the money and convinced her mom to split the cost with her.
ABC News picked up the story last week and shared this about the remarkable teenager:
She’s been on “The Ellen DeGeneres Show” where the host gifted her $10,000 to spend at Ace Hardware, in addition to a new clothes dryer. She’s been interviewed by ABC’s “World News” and NPR and even for a television show in South Korea. She’s accustomed to television crews and media types clamoring for her attention, her mother says.
By the time she is 18 and can legally own a home in Florida, Willow has a goal to own 10 houses.
Barry Habib with Mortgage Market Guide was a guest on the CNBC show Squawk Box yesterday and shared some great insight on why now is the “perfect storm” for homebuyers.
He points to three big reasons all renters should jump into homeownership:
1. Rent rates are increasing in some markets. It is becoming increasingly more affordable to own a home versus renting a similar home.
2. Interest rates have basically bottomed out. Could rates go lower? Yes they could with the announcement of QE3. But money is so cheap to buy a home that it makes sense to buy right now.
3. Tax benefits. On top of the really cheap mortgage money available today you also have several tax benefits of homeownership. The IRS Publication 530 details what can and cannot be deducted.
Watch the video below and leave a comment on your thoughts about the current housing market:
Zillow’s second quarter Real Estate Market Reports, released today, show home values increased 2.1% from the first to the second quarter of 2012 to $149,300 (Figure 1). On an annual basis, home values rose 0.2% from June 2011 levels (Figure 2), marking the first annual increase in U.S. home values since 2007. In addition to showing both quarterly and annual appreciation, national home values also rose for the fourth consecutive month, increasing 0.7%. Notably, home value appreciation in the second quarter was the highest since the fourth quarter of 2005.
Nationally, home values reached their bottom in February of 2012 and have since appreciated at very robust monthly growth rates. Despite encouraging monthly growth, we do not believe that this monthly rate is sustainable and expect it to taper off towards the end of the year. According to the Zillow Home Value Forecast, we expect national home values to appreciate by 1.1% over the next year (June 2012 to June 2013).
The housing market’s recovery continues to show tremendous variation market by market. Sixty-nine of the 157 markets covered by the Zillow Home Value Forecast are expected to see increases in home values over the next year, with the largest increases expected in the Phoenix metro (9.9%) and the Miami metro (6.1%). We believe that ninety-six out of the 157 markets have already hit a bottom in home values, including Boston, Miami, and Phoenix. In some of the hardest hit markets, the bottoming process has been quite different than we had initially expected. Due to very low inventory levels paired with greater consumer and investor appetite and low mortgage rates, home values have appreciated faster than anticipated in markets like Phoenixand Miami, creating a V-shaped recovery in home values.
The Zillow Real Estate Market Reports cover 167 metropolitan areas (metros) of which 98 showed quarterly home value appreciation. Five metros remained flat, while 64 metros show home value losses. Nearly one-third of metros covered by the Real Estate Market Reports posted annual increases in home values. The largest annual increase was in Phoenix, where home values rose 12.1% from the second quarter of 2011 to the second quarter of 2012. Phoenix is benefiting from high demand for homes from investors looking to convert them into rentals, high demand from mainstream buyers pulled back into the market by historical affordability (almost 43% below the historical average) and constrained supply due to high negative equity (55.5% of Phoenix homeowners with a mortgage were in negative equity in 2012 Q1) and natural resistance of sellers to sell at market bottom.
Overall, national home values are back to January 2004 levels, having fallen 22.9% since their peak in May of 2007.
The June Zillow Rent Index (ZRI) is up 5.2% from year-ago levels, and 68% of the 293 metropolitan areas covered by ZRI in this report experienced year-over-year gains. The rental market remains strong even as home values start to once again appreciate in many markets. Markets that saw extremely strong year-over-year rent increases include Philadelphia (11.9%), Chicago (11%),Baltimore (11%), and San Francisco (9.5%). Continually rising rents will increase consumer demand for home purchases, especially in this low mortgage rate environment.
The rate of homes foreclosed continues to decline in June with 5.8 out of every 10,000 homes in the country being liquidated (Figure 4). This is the lowest foreclosure pace we’ve seen since December 2007 when 5.5 out of every 10,000 homes were being liquidated. Nationally, foreclosure re-sales also continued to slow, making up 15.6% of all sales in June, down from 16.4% in May (Figure X). The decreasing prevalence of foreclosures in the monthly transactional mix is due to both seasonality (more non-foreclosure sales in the spring and summer) combined with the much slower pace of foreclosure liquidations over the past year. This lower level of foreclosure re-sales is contributing to home value appreciation, as these are usually sold at a discount and influence surrounding non-distressed sales. With foreclosure starts again increasing now that the National Foreclosure Settlement has been approved by the courts, we do expect some increase in foreclosure liquidations in the back half of this year, although lenders are being more aggressive in pursuing foreclosures alternatives for homes in the pipeline.
Nationally, we believe that housing has finally turned a corner, and our forecast calls for U.S. home values to increase by 1.1% over the next year. In general, we continue to believe that high levels of negative equity paired with higher than normal unemployment will keep foreclosure rates higher than normal for at least the next 2-3 years. In some markets, we believe this combination will temper near-term price appreciation and lead to a U-shaped recovery in home values.
In other markets, however, we believe the trajectory of home values will look more like a step-function characterized by cycles of price spikes and plateaus. In these markets, negative equity-induced supply constraints in combination with mainstream buyer demand and robust investor demand will lead to short-term price spikes (as we’re seeing now in Phoenix and Miami). These price spikes will free some homeowners from negative equity, allowing them to sell, thereby easing supply constraints and dampening prices until the cycle is repeated.
Downside risks to our outlook are that the pace of foreclosures increases more than expected, job growth becomes even more sluggish, or we have a political train wreck on the budgetary and tax issues we face at the end of this year. We, however, remain optimistic that low mortgage rates, high levels of affordability, rising rental prices, and slowly improving conditions in the overall economy will combine to keep the housing recovery on track, and we expect that both existing and new homes sales will continue to increase for the remainder of the year, being tempered only by low inventory levels (versus anemic demand).
See interactive data on Zillow’s Research page here.
Higher home prices are expected by 33% of consumers over the next year.
Fannie Mae’s monthly housing survey indicated 5% more people expect home prices to increase this month over the 27 percent surveyed last month who thought prices would increase this year.
Nearly half of consumers expect higher rental prices as well, the highest number registered by Fannie Mae since its monthly tracking began in June 2010. Americans’ rental price expectations for the next year continue to rise, reaching their record high level for the Fannie Mae survey this month.
The percentage of respondents who say it is a good time to buy rose by three points to 73 percent, the highest level in more than a year, while the percentage of respondents who say it is a good time to sell rose one point to 14 percent this month.
Consumers’ confidence about their own finances is stabilizing, with 44 percent expecting an improvement over the next year.
Higher Mortgage Rates Expected
There is an increasing share of consumers expecting both higher mortgage rates and home prices over the next 12 months.
Doug Duncan, Vice President and chief economist of Fannie Mae says, “Americans’ rental price expectations for the next year continue to rise, reaching their record high level for our survey this month.”
Duncan says, “Some may feel that renting is becoming more costly and that home ownership is a more compelling housing choice. Conditions are coming together to encourage people to want to buy homes.”
While the “sales of existing homes in January and February marked the strongest start to a year since 2007,” according to the combined Housing and Urban Development (HUD)/Treasury statement. “Data on home prices changed little from the previous month – marking a fifth month of seasonal lows.”
For further Fannie Mae survey findings, visit the Fannie Mae Monthly National Housing site.
WASHINGTON (AP) — Five years after the U.S. housing bust sent sales and prices plunging, the spring home-buying season is pointing to a long-awaited recovery.
Reduced prices, record-low mortgage rates, higher rents and an improving job market appear to be emboldening many would-be buyers. Open houses are drawing crowds. A wave of foreclosures is leading investors to grab bargain-priced homes.
And many people seem to have concluded that prices won’t drop much further. In some areas, prices have begun to tick up.
Interviews with more than two dozen potential buyers, sellers, brokers, Realtors and economists suggest that confidence is up and that sales will move slowly but steadily higher.
“The biggest challenge that we’ve had over the past four years is fear — fear that the economy is collapsing, that property values are collapsing, that the world is coming to an end,” says Mark Prather, a broker at ERA Buy America Real Estate in La Palma, Calif. “The fear factor is all but gone.”
Prather says the number of prospective buyers who contacted his company last month was about 35 percent more than a year ago.
The spring buying season got an early lift-off from an uncommonly warm January and February — a winter that was the best for sales of previously occupied homes in five years. Permits to build houses and apartments rose in February to their highest level since 2008.
“People feel much more confident,” said Steve Brown, co-owner of real estate company Irongate Inc. of Dayton, Ohio, who says sales jumped more than 16 percent for the first two months of 2012 over the same period last year. “There’s no question there’s a good feeling in the marketplace.”
Some analysts detected a slight uptick in prices for February and March. CoreLogic, a real estate data firm, says prices for homes not at risk of foreclosure — about two thirds of the market — rose 0.7 percent in February. It was the first increase in four years. Price gains occurred both in some hard-hit areas, such as Phoenix, and some still-thriving areas like New York and Washington.
In Miami, the average sales price has surged 14 percent in the past year, according to Trulia, a real estate data firm. In Phoenix, the average is up 13 percent, in Pittsburgh 9 percent.
Earnings reports Friday from two big banks suggested that more people are taking out mortgages. JPMorgan Chase issued 6 percent more mortgages from January through March than it did a year ago and got 33 percent more applications. Wells Fargo issued 54 percent more mortgages and received 84 percent more applications.
Still, few think the housing industry is nearing a return to full health. For that to happen, a robust job market would be needed. More hiring would give more people the money and job security to buy. That would help boost sales and prices.
Such areas as Atlanta, suburban Las Vegas and central California show few signs of recovery. And in some others — from Seattle to Cleveland — home prices have continued to slip. The average has dropped 9 percent in Seattle over the past 12 months and 7 percent in Cleveland.
But in many parts of the country, including thriving areas of Boston, Dallas and Seattle, confidence is rising along with prices. Among the reasons:
Also fueling interest are signs that home values are finally stabilizing. One factor that had slowed purchases after the housing boom ended in late 2006 was fear that a home would lose value soon after its purchase.
But the price declines slowed toward the end of 2011, according to the Wells Fargo/Case-Shiller home price index. And CoreLogic says the average price nationally rose slightly in January and February.
“Unless prices went down, I don’t think we would have ever been able to afford a home,” said John Henschel, 37, an information technology consultant who will move with his family into a five-bedroom house in Wheaton, Ill., in May. “But we feel like prices aren’t going to go back down. We’re confident. So why not?”
When the landlord on their Chicago apartment told them he was selling it, Henschel and his wife decided it was time to buy. The home they bought for nearly $450,000 could have fetched more than $570,000 six years ago, according to housing website Zillow.com.
On a rainy Saturday this month in long-struggling Riverside, Calif., 12 families visited a three-bedroom house priced at $199,999. Ten others stopped by in the first hour of the next day’s open house. By the end of the weekend, two buyers had made offers.
“We’re seeing more buyer activity this spring than we’ve seen in probably four years,” said Liane Thomas, the broker who was showing the house.
Prices in the area could rise in coming months because the supply of homes for sale in Riverside is down — from nearly 19,000 last year to 13,000 in February.
Many potential buyers are hunting for deals in places that were especially hurt by the housing bust. In Sarasota, Fla., which boasts wide sugar-sand beaches, condos are selling for an average of $325,000, compared with more than $550,000 at the height of the boom, said Marc Rasmussen, a broker.
Homes nearing foreclosure account for nearly half of all properties on the market, according to the Campbell/Inside Mortgage Finance HousingPulse survey. That compares with 10 percent in healthy economies. Many are receiving multiple offers because their prices have plunged.
In Phoenix, a foreclosed home offered for $77,000 that had been vandalized received 21 offers last month at or near the asking price — roughly the price it sold for. The average time a home sits on the market in Phoenix has dropped from 114 days last year to 90 days, according to the Cromford Report, a data research group.
In suburban Washington, D.C., Rory Obletz and his wife have been saving to buy after renting for six years. Obletz, 27, failed in two previous bids for single-family homes. He’s hoping a third bid — about $10,000 above the asking price of $399,000 for a home in Silver Spring, Md. — will succeed this month.
“One home we went to, it was under contract by the time we walked out of the house,” Obletz said. “If you really want to get something, you don’t have a lot of time to think about it.”
It isn’t just bargain-hunting families seeking homes. Investors are increasingly buying single-family houses, fixing them up and re-selling them or converting them into rentals.
Investors are out-bidding many first-time buyers on cheaper homes in particular. Sales of homes between $100,000 and $250,000 have jumped nearly 19 percent over the past year. For homes between $250,000 and $500,000, sales are up 13 percent.
More expensive homes, from $500,000 to $750,000, whose sales tend to contribute the most to the U.S. economy, are up a smaller 6.7 percent.
For buyers seeking to move up to a bigger home or to relocate, the toughest challenge is often selling the home they’re in. According to CoreLogic, about 11 million homeowners are “underwater” — they owe more on their mortgage than their home is worth.
Yet for first-timers like Obletz, who have been saving and watching as homes have become more affordable, the time feels right.
“Rent is a little more expensive, and we have the money, so we might as well jump on it,” he says.
_
By ALEX VEIGA, AP Real Estate Writers.
Veiga reported from Los Angeles. Associated Press Writer Tamara Lush in Sarasota, Fla., contributed to this report.
Copyright © 2012 The Associated Press. All rights reserved.